France’s rising debt fuels higher borrowing costs as bond markets react
France’s borrowing costs have jumped sharply amid the most severe social unrest the country has seen in decades. Yields on French government bonds have climbed to their highest levels in almost 25 years, as investors demand larger returns for holding French debt. This rise signals a growing belief among bond traders that lending to France is becoming increasingly risky.
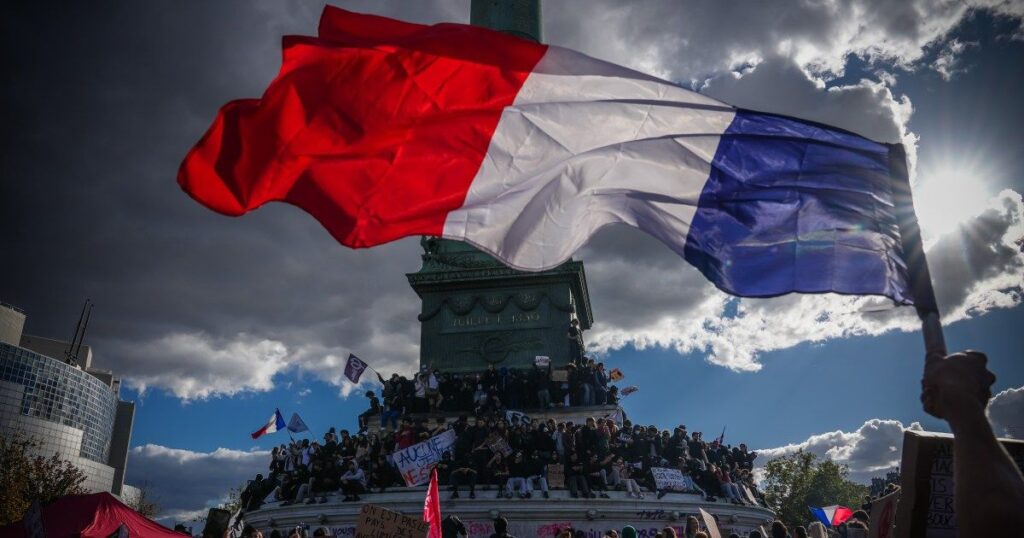
The government is struggling with a widening gap between spending and revenue, while a fragmented political landscape remains sharply divided over how to close the deficit. Hundreds of thousands of demonstrators, some involved in riots and looting, have taken to the streets to oppose proposed budget cuts and to call for more spending on cost‑of‑living relief and public services such as education. France’s national debt is now at its highest level since the immediate post‑World War II period, approaching 120 percent of gross domestic product (GDP).
Bonds are essentially loans to a government or corporation. Countries regularly tap bond markets to finance spending that exceeds tax revenues. In return for buying a bond, an investor receives regular interest payments and the principal at a predetermined future date. These securities can be traded among investors before maturity. Bond prices move with interest rates, inflation expectations and confidence in the issuer’s ability to repay; when prices rise, yields fall, and the opposite occurs.
France’s 10‑year bond yield has risen by more than 130 basis points since June, surpassing 4.9 percent. The cost of borrowing is now at its highest level since 2002, consuming a larger share of tax revenues that could otherwise support essential services like education and health care. While France’s debt load is relatively high, the absolute amount owed is only one factor that investors consider when pricing risk. Confidence in a country’s capacity to meet its obligations is shaped by the strength of its economy, the balance between external and domestic debt, and the effectiveness of its political system.
“The sustainability of sovereign debt is rarely determined by its absolute level alone,” said Victor Lequiller, president of BSI Economics, a Paris think‑tank. “It depends far more on its trajectory, structure, and broader economic and financial context.” In France’s case, the current paralysis of the political system is a major source of concern for bond markets.
In the divided National Assembly, Prime Minister Sébastien Lecornu, appointed by President Emmanuel Macron under the semi‑presidential system, is locked in a legislative battle to pass next year’s budget, which includes 54 billion euros in savings. Far‑right leader Marine Le Pen of the National Rally and far‑left candidate Jean‑Luc Mélenchon of France Unbowed, the two leading contenders for next year’s presidential election, oppose Lecornu’s plan, although the government could invoke a constitutional clause to bypass parliament if necessary.
Antonio Fatas, an economics professor at INSEAD, told Al Jazeera: “Are the French numbers much worse than other countries? No, but marginally they are worse, and the real difficulty here is that the political situation is such that the current government does not have an easy path to put together a budget that makes sense from a debt‑sustainability point of view.” He added that this political impasse makes France a special case, explaining why markets are especially nervous.
France’s national debt now stands at roughly 3.6 trillion euros, about 119 percent of GDP, up from 98 percent in 2019, the year before the COVID‑19 pandemic began. More worrisome to investors is the rapidly expanding deficit, projected to reach 5.4 percent of GDP in 2026, well above the European Union average of just over 3 percent. This figure represents the gap between government spending and income.
France has a long tradition of left‑wing politics and activism and maintains one of the largest public sectors among developed nations. Government expenditure accounts for about 57 percent of GDP, second only to Finland among OECD countries. Public pensions are a particularly large component, representing 14 percent of GDP, a share likely to grow as the working‑age population declines in coming decades.
“Ironically, President Macron has long discussed the reforms needed to improve the fiscal outlook and avoid attracting the ire of bond investors,” said Alex Dryden, a macroeconomist at the Centre for Sustainable Finance, SOAS University of London. “From 2017 onward, Macron has spoken of the need for pension reforms to ease the fiscal burden, but this is a lightning‑rod political issue.”